
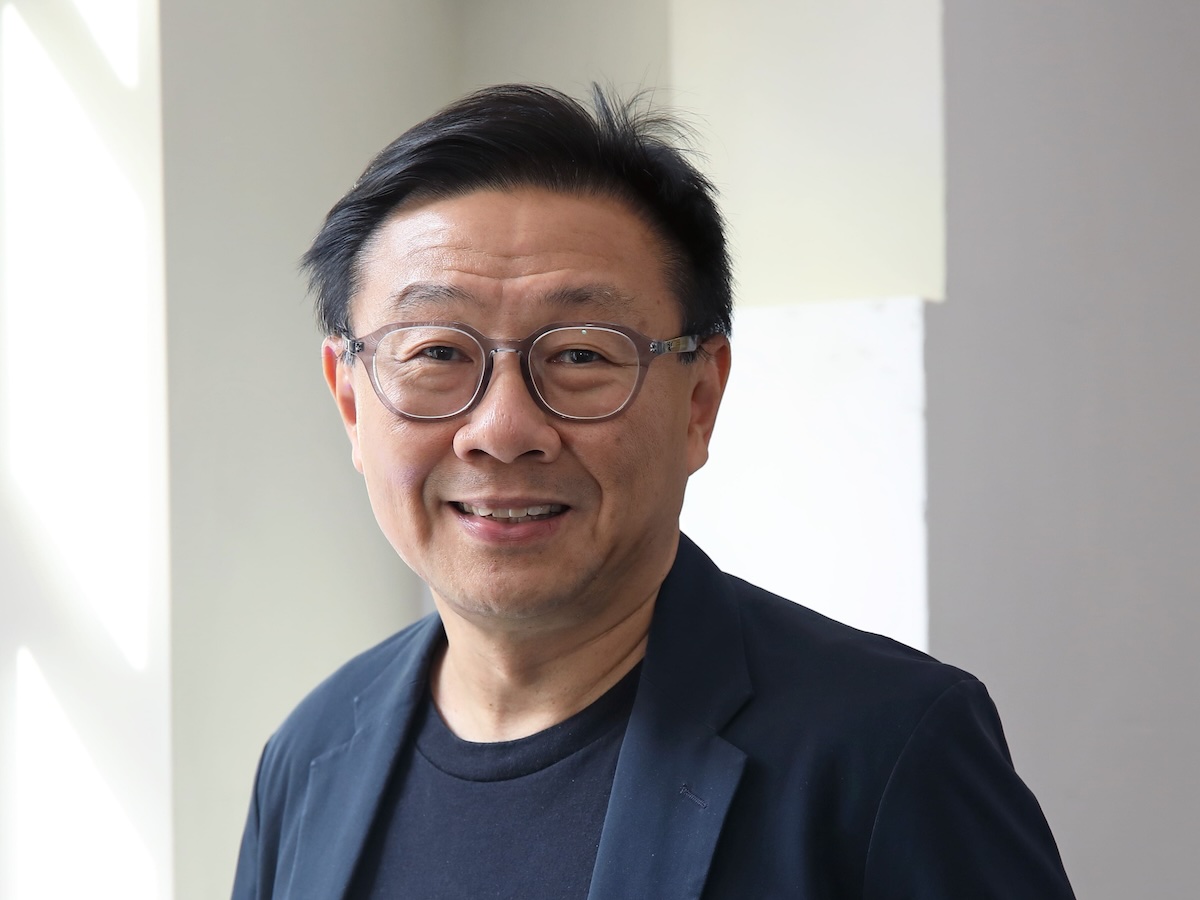
Boon Chee Loo (pictured) joined Bridge Alliance in 2020, just as the Covid-19 pandemic reached Asia. He became CEO in April 2026, after helping the alliance broaden its work from roaming coordination into regional platforms for IoT, communications services and network APIs.
In this interview, Loo discusses how Bridge Alliance helps operators serve multinational businesses, the rapid growth in connected vehicle data, and the practical challenges of making services work across different markets. Sean Gowran, Aeris’ APAC sales VP, also joined the conversation, as Loo explains the alliance’s approach to APIs, security and AI - and why he sees roaming continuing to complement local connectivity.
Developing Telecoms: You joined Bridge Alliance in 2020, just as Covid-19 hit Asia. What attracted you to the organisation?
Boon Chee Loo: I had spent close to 30 years in telecoms, working across consumer, enterprise and digital businesses. I was excited by the opportunity to apply that experience to help operators at a regional level.
Bridge Alliance was originally focused on roaming and the frameworks that help operators work together. Under the previous CEO, Geok Chwee Ong, the organisation began to pivot towards becoming a regional product house: building platforms that help member operators compete more effectively in their markets. The organisation needed someone familiar with productisation and developing regional products, and that was a good fit with my background.
The IoT journey had already begun, and I helped establish the CPaaS platform and, more recently, the Telco API Exchange.
Developing Telecoms: What are the alliance’s main areas of activity today?
Loo: Roaming is where Bridge Alliance started. We created frameworks to help operators work together, deliver a good experience to consumers and develop effective cost structures.
As the alliance grew, we also saw an opportunity in group sourcing. For items that are not highly differentiated from one market to another - such as fibre cable, IPX bandwidth and testing tools - members can negotiate collectively and seek savings.
Over the past decade, we have also built platforms to help operators compete in the enterprise market. That includes IoT, CPaaS and APIs. Those are the five pillars we have today.
AI is now a major topic, although we are still working out what the alliance can do collectively. We can look at AI capabilities that sit on top of our existing services, and at whether members have common needs that could benefit from group sourcing.
Developing Telecoms: Where can cooperation between operators make the biggest practical difference for businesses?
Loo: IoT is a good example. Historically, many IoT solutions were deployed within one country. Each operator had its own platforms, systems and processes. But manufacturers increasingly want to offer products regionally.
Consider a car manufacturer that wants connectivity embedded in vehicles before they are delivered to Singapore, Malaysia or Thailand. The connectivity may support telemetry or software updates, and the customer wants to arrange it at the point of manufacture. As vehicles become more connected - and potentially more autonomous - the demand for connectivity and bandwidth will grow.
The commercial model has to be simple: the customer should be able to subscribe and get connectivity. The technical implementation must also be straightforward. If a customer has to deal separately with every operator’s systems, platforms and processes, it becomes daunting. We need to provide a single point of coordination and an orchestration layer that hides much of that complexity.
Regulation differs between countries, too. Local operators bring knowledge of their own markets, helping customers navigate requirements that may not always be easy to understand from outside.
Developing Telecoms: How do you measure whether this regional coordination is working?
Loo: One indicator is the number of regional deals we enable. We also look at the connections and bandwidth usage associated with those deals, including year-on-year growth in SIM connections.
For the period from August 2025 to August 2026, we reported 40% year-on-year growth in regional IoT SIM connections.
Sean Gowran: Data usage alsogrew by 65% over the same period.
Developing Telecoms: What is driving that growth?
Gowran: Automotive is a major driver, particularly the growth in electric vehicles. An internal-combustion car might use around 100 megabytes of data a month, while an electric vehicle can use around two gigabytes. Some models reach seven or eight gigabytes a month.
Loo: The way vehicles use connectivity is changing. At first, it was mainly for telemetry and software updates. There is now interest in using connectivity for in-car entertainment, which could increase data consumption further. Autonomous vehicles would require still more.
Developing Telecoms: Are networks across Asia Pacific ready for autonomous vehicles?
Loo: Autonomous vehicles are still at an early stage, so there is time for networks to develop. They will require low latency so that a vehicle can get a response quickly when it encounters a problem. Not every country is ready, but networks are progressing, including through the deployment of 5G standalone.
There is also a commercial question: how to support high data usage per SIM when the traditional business model may have been designed for much lower usage.
Developing Telecoms: What have you learned about managing the growth in connected vehicles?
Loo: One lesson is that software updates need coordination. A car manufacturer might decide to update 100,000 vehicles at once. But if that happens during peak network hours, it could affect the update and other customers using the network.
We have learned to coordinate updates and, where appropriate, stagger them so they happen outside peak periods. Sean mentioned that the software can often be downloaded over a longer period without affecting when it is installed. Throttling the update traffic can help prevent sudden spikes in network demand.
Developing Telecoms: Turning to network APIs, what can enterprises do through the Bridge Alliance API Exchange?
Loo: Our approach to APIs has changed as we have learned what customers need. Traditionally, we have aimed to have one leading operator in each market as a member, so that it can compete and differentiate locally.
But that is not always enough for APIs. An enterprise changing its app or workflow wants broad market coverage. A bank is unlikely to make a major change if the service only reaches 30% of its customers.
So, for APIs, we have shifted to working with all operators in each country we target. We currently have operators in Thailand, Taiwan, Malaysia and Indonesia on the API Exchange. We have made Number Verify and SIM Swap APIs available because these are capabilities many operators can provide in a standard form, using specifications defined by CAMARA.
The enterprise can integrate once and use the API across the markets covered. We plan to add more markets, including Singapore, India, Japan, Vietnam and Australia. If everything goes well, our aim is to cover at least 10 Asian markets by April.
Developing Telecoms: What needs to happen for network APIs to become a meaningful source of revenue for operators?
Loo: First, operators need to be organised and harmonised. If the service is not consistent, enterprises will not use it at scale. We need enough markets and operators participating. That is a major focus for the first two years.
Second, customers need to know the APIs are available and understand how they can help their businesses - for example, by improving productivity or customer experience.
There is also a commercial challenge with Number Verify. It is often compared with SMS one-time passwords, which businesses already pay for. If they switch to an API, they may expect the price to be similar, so there can be price pressure.
Other APIs may create more value. In developing markets, for example, financial institutions may want additional signals when assessing people who have little or no traditional credit history. Telco data could potentially provide useful indicators, such as patterns of bill payment or account balance. That could give a financial institution a different kind of information to consider when assessing a loan.
Developing Telecoms: Beyond the technology, how does Bridge Alliance organise operators to support multinational IoT deals?
Loo: We have a framework for handling regional requirements, including a “lead operator” and “supporting operator” model. If a member comes across a deal that needs coverage in several countries, there are already agreed rules, capabilities and platforms to support it.
The alliance pieces these elements together for operators and ecosystem partners. Customers get a more consistent way to access services, with much of the complexity handled behind the scenes.
Developing Telecoms: Automotive is a major IoT driver. Which other industries could contribute to growth?
Loo: We believe more and more objects will be connected. China is an important source of manufacturing, so we are speaking with chipset and module makers. If connectivity is embedded in a module, it can be built into many different products.
That could mean more connected appliances, cameras and home devices. We are also seeing more autonomous objects, from vehicles to robots. Anything autonomous will require connectivity, so we want to work with the companies making those products.
Developing Telecoms: Does this shift towards local connectivity mean roaming will become less important?
Loo: Roaming and local connectivity complement each other. Local connectivity is our preference where it is available, because it can provide good coverage, experience and service. But not every market can immediately support a local arrangement. Roaming can serve those markets and remains an important capability.
Developing Telecoms: What role can an alliance play in closing the connectivity gap in emerging markets?
Loo: We leave infrastructure investment to individual operators. Our members are leading operators in their markets, and they are responsible for maintaining and developing their networks.
Bridge Alliance focuses on the orchestration layer: making it easier for enterprise customers to consume connectivity across markets. We also work with partners to ensure our platforms keep pace with the technical capabilities available in each market, including 5G standalone and, in future, 6G.
Developing Telecoms: How are you approaching cybersecurity and fraud prevention?
Loo: Operators have their own cybersecurity programmes. For IoT, our partner Aeris has launched IoT Watchtower, which adds security capabilities to the IoT connectivity we provide.
Developing Telecoms: What opportunities do you see for AI, and where can Bridge Alliance contribute?
Loo: Our members are individually exploring AI for areas such as autonomous networks, workflow optimisation and personalisation. Network autonomy is still developing; I do not think networks are fully autonomous at this stage.
For the alliance, there are a few possible areas. We can help make AI capabilities available alongside our existing pillars. For example, AI voice bots or chatbots could be integrated with our CPaaS platform for operators to offer to enterprise customers. AI applications that use the APIs available through the exchange could also be supported.
A further possibility is a kind of token exchange that could bring together different large language models and find an appropriate route and cost for an AI application. That work is still in progress; we have not yet determined exactly what it should look like.
Developing Telecoms: Does the potential risk of AI make operators cautious about deploying it?
Loo: It makes members more careful about selecting and governing AI tools. Operators are licensed businesses, so a deployment that causes disruption could put their licences at stake.
When we consider adding AI applications to CPaaS, for example, there are processes and checklists to follow. The aim is to enable implementation while making sure there is a clear process to govern it.